
A blog for discussing startups, the key figures in the industry and some of their foundational essays and other texts.

You can purchase Peter Thiel's book below:

Peter Thiel
Peter Thiel, cofounded Paypal and invested in Facebook, amongst other things. He is vocal, and always interesting and original, on a range of topics, but here we will discuss hisThe essay captures a key idea in the web of ideas that constitute Thiel's view of startups. Thiel explores these ideas at length in 0 to 1, but this essay is actually a chapter from the book that the Wall Street Journal published, and in many ways it gives us a good sense of the larger theory.
In 1933, Edward Chamberlain (in Theory of Monopolistic Competition) introduced the idea of product differentiation. To grossly simplify the argument, a firm can charge a premium for a product to the extent that the product is differentiated in valuable dimensions from other commodity products. In an extreme case, the firm could have a monopoly on the service or product, and can charge monopolistic prices.
Monopolies, Profit and Competition
Thiel points out how it is possible to produce such a monopoly: by coming up with a novel product or service. And coming up with a novel product or service (from 0 to 1), is not easy because by definition, it has never been done before.I'm not interested in illegal bullies or government favorites: By "monopoly," I mean the kind of company that is so good at what it does that no other firm can offer a close substitute.(Peter Thiel)He contrasts this with taking an idea that already exists and simply doing more of it by moving it to a different location, or making incremental improvements on it in scale (1 to n). The problem with this kind of business is that it is hyper-competitive and profits quickly erode.
Q: What would Thiel make of companys that excel at going from 1 to n? Consider that Rocket Internet has a thriving business openly based on copying other ideas.
Morality
Thiel spends some time defending monopolies. He claims that our traditional loathing for monopolies only applies in a "static" world where they rent collect in exchange for little added value.But the world we live in is dynamic: We can invent new and better things. Creative monopolists give customers more choices by adding entirely new categories of abundance to the world. Creative monopolies aren't just good for the rest of society; they're powerful engines for making it better. (Peter Thiel)
Framing the "relevant market"
One of the interesting points he brings up is that a monopoly is defined against a market. He gives two examples that illuminate in different ways. He points out that monopolistic companies define the market as large as possible so as not to be accused of legal monopolies, and companies with small markets define the market as narrowly as possible to appear more dominant.Suppose you want to start a restaurant in Palo Alto that serves British food. "No one else is doing it," you might reason. "We'll own the entire market." But that is only true if the relevant market is the market for British food specifically. What if the actual market is the Palo Alto restaurant market in general? And what if all the restaurants in nearby towns are part of the relevant market as well? (Peter Thiel)
Find a monopoly
Peter Thiel ends with a great summary, so I'll lets say it.All happy companies are different: Each one earns a monopoly by solving a unique problem. All failed companies are the same: They failed to escape competition. (Peter Thiel)Q: I want to interrogate Thiel's central thesis -- that you should come up with a truly original idea, to go from 0 to 1.
He puts forward examples like Google as an example. But Google was not the first search engine, and there were other search engines at the time. Thiel's most famous investment, Facebook, dominates social networks now but it there were dozens of social network at the time, and the market was dominated by MySpace, which itself had overthrown Friendster.
Are these still good examples of going from 0 to 1?
You can purchase Peter Thiel's book below:
This is a discussion of Peter Thiel's Wall Street Journal Essay, Competition Is for Losers. It is part of a series of foundational texts on What is a startup business?
You can purchase Peter Thiel's book below:
Peter Thiel
Peter Thiel, cofounded Paypal and invested in Facebook, amongst other things. He is vocal, and always interesting and original, on a range of topics, but here we will discuss hisThe essay captures a key idea in the web of ideas that constitute Thiel's view of startups. Thiel explores these ideas at length in 0 to 1, but this essay is actually a chapter from the book that the Wall Street Journal published, and in many ways it gives us a good sense of the larger theory.
In 1933, Edward Chamberlain (in Theory of Monopolistic Competition) introduced the idea of product differentiation. To grossly simplify the argument, a firm can charge a premium for a product to the extent that the product is differentiated in valuable dimensions from other commodity products. In an extreme case, the firm could have a monopoly on the service or product, and can charge monopolistic prices.
Monopolies, Profit and Competition
Thiel points out how it is possible to produce such a monopoly: by coming up with a novel product or service. And coming up with a novel product or service (from 0 to 1), is not easy because by definition, it has never been done before.I'm not interested in illegal bullies or government favorites: By "monopoly," I mean the kind of company that is so good at what it does that no other firm can offer a close substitute.(Peter Thiel)He contrasts this with taking an idea that already exists and simply doing more of it by moving it to a different location, or making incremental improvements on it in scale (1 to n). The problem with this kind of business is that it is hyper-competitive and profits quickly erode.
Q: What would Thiel make of companys that excel at going from 1 to n? Consider that Rocket Internet has a thriving business openly based on copying other ideas.
Morality
Thiel spends some time defending monopolies. He claims that our traditional loathing for monopolies only applies in a "static" world where they rent collect in exchange for little added value.But the world we live in is dynamic: We can invent new and better things. Creative monopolists give customers more choices by adding entirely new categories of abundance to the world. Creative monopolies aren't just good for the rest of society; they're powerful engines for making it better. (Peter Thiel)
Framing the "relevant market"
One of the interesting points he brings up is that a monopoly is defined against a market. He gives two examples that illuminate in different ways. He points out that monopolistic companies define the market as large as possible so as not to be accused of legal monopolies, and companies with small markets define the market as narrowly as possible to appear more dominant.Suppose you want to start a restaurant in Palo Alto that serves British food. "No one else is doing it," you might reason. "We'll own the entire market." But that is only true if the relevant market is the market for British food specifically. What if the actual market is the Palo Alto restaurant market in general? And what if all the restaurants in nearby towns are part of the relevant market as well? (Peter Thiel)
Find a monopoly
Peter Thiel ends with a great summary, so I'll lets say it.All happy companies are different: Each one earns a monopoly by solving a unique problem. All failed companies are the same: They failed to escape competition. (Peter Thiel)Q: I want to interrogate Thiel's central thesis -- that you should come up with a truly original idea, to go from 0 to 1.
He puts forward examples like Google as an example. But Google was not the first search engine, and there were other search engines at the time. Thiel's most famous investment, Facebook, dominates social networks now but it there were dozens of social network at the time, and the market was dominated by MySpace, which itself had overthrown Friendster.
Are these still good examples of going from 0 to 1?
You can purchase Peter Thiel's book below:
This is a discussion of Marc Andreessen's "The only thing that matters", also sometimes entitled "Product Market Fit." (June, 2007) It is part of a series of discussions of foundational texts on What is a startup business?
Marc Andreessen co-authored Mosaic, the first web browser, founded Netscape, and Andreessen-Horowitz, the venture fund. He is outspoken and active on twitter.
Andreessen opens by declaring that the post is about "the only thing that matters for a new startup." Towards the end of the essay he tells us:
This is a counterintuitive claim. Many people who discuss startups will claim that the founder, or the founding team, is the single most important thing and that "smart" people will figure out how to make something successful.
I just googled what to look for in a startup team and this is the first link that appeared: 5 things angel investors should look for in a startup Note that team shows up twice on this list (#1 all star team and #4 integrity).
Andy seems to be saying that the market is more important. Andreessen summarizes the logic in two key statements:
Contrast: This view contrasts with the view that the right founder will figure it out, but there is a subtle variation. Chris Dixon has proposed that you need the right founder for a particular market, and that not all founders are suited to all markets. I don't think of this as an opposing view, so much as an interesting addition.
Q: Although I think that many people have said picking the right founder is key, I cannot recall a single key text where this is clearly laid out. Can the reader recall such a text?
The essay culminates in a piece of advice though:
Q: I wonder to what extent this contradicts the advice of others. I think this is compatible with Graham's advice to focus on growth. It is not compatible or incompatible with Thiel's advice to earn a monopoly by solving a unique problem. There is nothing that indicates the problem or solution has to be unique. That is more of an issue for Thiel who hasn't specified what he means by his uniqueness criterion. There is also nothing here about having a monopoly.
Marc Andreessen
Product/Market Fit
Andreessen opens by declaring that the post is about "the only thing that matters for a new startup." Towards the end of the essay he tells us:
The only thing that matters is getting to product/market fit. (Marc Andreessen, all bold in original)He begins with some context. He divides the causes of startup success into three components: team, product and market, which he borrows from Andy Rachleff, and goes on to quote Andy:
- When a great team meets a lousy market, market wins
- When a lousy team meets a great market, market wins.
- When a great team meets a great market, something special happens. (Andreessen quoting Andy Rachkeff)
This is a counterintuitive claim. Many people who discuss startups will claim that the founder, or the founding team, is the single most important thing and that "smart" people will figure out how to make something successful.
I just googled what to look for in a startup team and this is the first link that appeared: 5 things angel investors should look for in a startup Note that team shows up twice on this list (#1 all star team and #4 integrity).
Markets trump founders
In a great market -- a market with lots of real potential customers -- the market pulls product out of the startup. (Marc Andreessen)and
Conversely, in a terrible market, you can have the best product in the world and an absolutely killer team, and it doesn't matter -- you're going to fail. (Marc Andreessen)I think the second statement is non-controversial, and the primary reason that people fail to start a business is that they don't make things people want. The first, though, is interesting. It suggests that if you pick the right product or service, you might succeed in spite of a mediocre team. (Mediocre teams rejoice).
Contrast: This view contrasts with the view that the right founder will figure it out, but there is a subtle variation. Chris Dixon has proposed that you need the right founder for a particular market, and that not all founders are suited to all markets. I don't think of this as an opposing view, so much as an interesting addition.
Q: Although I think that many people have said picking the right founder is key, I cannot recall a single key text where this is clearly laid out. Can the reader recall such a text?
Advice
The essay culminates in a piece of advice though:
When you are BPMF [before product/market fit] , focus obsessively on getting to product/market fit.
Do whatever is required to get to product/market fit. Including changing out people, rewriting your product, moving into a different market, telling customers no when you don't want to, telling customers yes when you don't want to, raising that fourth round of highly dilutive venture capital -- whatever is required.
When you get right down to it, you can ignore almost everything else. (Marc Andreessen)The best part of this is the singular goal he proposes.
Q: I wonder to what extent this contradicts the advice of others. I think this is compatible with Graham's advice to focus on growth. It is not compatible or incompatible with Thiel's advice to earn a monopoly by solving a unique problem. There is nothing that indicates the problem or solution has to be unique. That is more of an issue for Thiel who hasn't specified what he means by his uniqueness criterion. There is also nothing here about having a monopoly.
Before we start to talk about what a startup business is, lets talk about why it is important to define it.
Relying on commonplace assumptions about a set of features will lead to absurd claims as to what constitutes a startup.
The commonplace idea of a startup is a new business, but there is a myth around the startup. Eric Ries in What's a startup? describes the mythology of the startup in the following terms:
But a new business, even a risky one, and hard working founders fall short of the definition of startup. The great counter example here would be the restaurant. Restaurants are risky, and require people to work "incomprehensible hour", but there seems to be wide agreement that a restaurant is not what people mean by a startup. Paul Graham uses it in his essay Startup=Growth, as an example of what is not, in his terms, a startup:
Peter Thiel also uses the restaurant business as a counter-example in his essay Competition Is for Losers:
Note that Thiel isn't explicitly talking about the definition of a startup, but is rendering advice.
Definitions and advice
Implicit in the definition of a startup is a normative claim about what you ought to do as a startup. When Graham talks about growth as definitive of a startup, he follows up to tell us that you should do what you can to grow a startup. When Thiel advises startups to produce a large innovation that takes us from "0 to 1", he implies that a startup, as opposed to say a restaurant, is a company that engages in an attempt to go from "0 to 1."
There isn't one main definition of a startup, but there are some key practitioners and theorists in the field who have come up with influential definitions. They happen to be men but if a reader has women to suggest, I will gladly add them to this list. They are many important and influential women in the field, but I haven't come across a definition of startups from them.
Here are some of the people from the "Seminal Essays" section.
This is from Paul Graham's essay "Startup=Growth".
This is from Marc Andreesen on the Product Market fit.
From Peter Thiel's Competition Is for Losers.
From Steve Blank on what's a startup.
from Eric Reis' on What is startup.
Define a startup
Definitions are tricky, because they often exclude examples one wishes to include, and they include examples that one wishes to include.Relying on commonplace assumptions about a set of features will lead to absurd claims as to what constitutes a startup.
What isn't a startup?
The commonplace idea of a startup is a new business, but there is a myth around the startup. Eric Ries in What's a startup? describes the mythology of the startup in the following terms:
What all of these pictures have in common is a narrative that goes something like this: scrappy outsiders, possessed of a unique genius, took outrageous risks and worked incomprehensible hours to beat the odds. (Ries)
But a new business, even a risky one, and hard working founders fall short of the definition of startup. The great counter example here would be the restaurant. Restaurants are risky, and require people to work "incomprehensible hour", but there seems to be wide agreement that a restaurant is not what people mean by a startup. Paul Graham uses it in his essay Startup=Growth, as an example of what is not, in his terms, a startup:
Millions of companies are started every year in the US. Only a tiny fraction are startups. Most are service businesses—restaurants, barbershops, plumbers, and so on. These are not startups, except in a few unusual cases. (Graham)
Peter Thiel also uses the restaurant business as a counter-example in his essay Competition Is for Losers:
Imagine you're running one of those restaurants in Mountain View. You're not that different from dozens of your competitors, so you've got to fight hard to survive. If you offer affordable food with low margins, you can probably pay employees only minimum wage. And you'll need to squeeze out every efficiency: That is why small restaurants put Grandma to work at the register and make the kids wash dishes in the back. (Peter Thiel)
Note that Thiel isn't explicitly talking about the definition of a startup, but is rendering advice.
Definitions and advice
Implicit in the definition of a startup is a normative claim about what you ought to do as a startup. When Graham talks about growth as definitive of a startup, he follows up to tell us that you should do what you can to grow a startup. When Thiel advises startups to produce a large innovation that takes us from "0 to 1", he implies that a startup, as opposed to say a restaurant, is a company that engages in an attempt to go from "0 to 1."
There isn't one main definition of a startup, but there are some key practitioners and theorists in the field who have come up with influential definitions. They happen to be men but if a reader has women to suggest, I will gladly add them to this list. They are many important and influential women in the field, but I haven't come across a definition of startups from them.
Here are some of the people from the "Seminal Essays" section.
Paul Graham
Paul Graham: A startup is a company designed to grow fast. Being newly founded does not in itself make a company a startup. Nor is it necessary for a startup to work on technology, or take venture funding, or have some sort of "exit". The only essential thing is growth. Everything else we associate with startups follows from growth. (Graham)
This is from Paul Graham's essay "Startup=Growth".
Marc Andreesen
The only thing that matters is getting to product/market fit. (Andreesen)
This is from Marc Andreesen on the Product Market fit.
Peter Thiel
All happy companies are different: Each one earns a monopoly by solving a unique problem. All failed companies are the same: They failed to escape competition. (Thiel)
From Peter Thiel's Competition Is for Losers.
Steve Blank
Steve Blank: a startup is an organization formed to search for a repeatable and scalable business model. (Blank)
From Steve Blank on what's a startup.
Eric Reis
A startup is a human institution designed to deliver a new product or service under conditions of extreme uncertainty. (Reis)
from Eric Reis' on What is startup.
This is a discussion of Steve Blank's impressively succinct essay What's A Startup?. It is part of a series of discussions of foundational texts on What is a startup business?
You can buy his book, The Startup Owner's Manual here:
Blank is known primarily as a theoretician, although he has founded and advised many companies. His ideas have been very influential in the culture.
Blank has been thinking about startups for a while, so his blog post are focused, but peppered with reference to other areas where he expands on the topic.
He gets right to the point:
Q: Peter Thiel seems to disagree with Blank's model. In particular he advises startups to have big bold plans, that can be modified indefinitely, which deliver an enormous innovation that earns a monopoly. Blank doesn't think this contradicts his own view. Do readers think there is a fundamental distinction here?
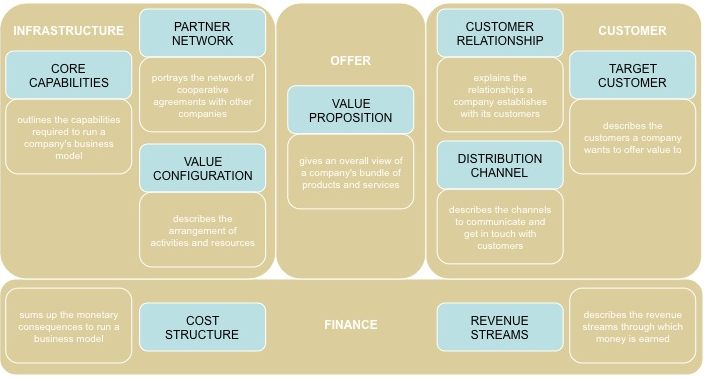
Blank is a fan of the Alexander Osterwalder's Business Model Canvas , which is a template to organize the components of a business.
Blank has specific advice on the role of a founding team.
Contrast: Although Thiel has claimed that this advice contradicts to come up with a long term plan, the tenure of the plan doesn't seem to be a central component of Blank's thesis. There is something about the MVP that feels small and timid, compared to Thiel's idea of going from 0 to 1 which feels ambitious and large in scale. The question is, if Blank had used a different word -- Initial Hypthesis Product, for instance -- would there still be a fundamental disagreement?
Q: Blank realizes of course that experimentation can be very expensive. You can't usually launch an entire business to see if customers like it, so his idea is to put out a really simple minimal viable product and use that to test it.
The big criticism -- and I am not the first to make it -- is this contrast directly with advice from other people.
Famously, Steve Jobs said in an interview:
Blank is well aware of this criticism, but I don't know that he fully takes on the problem.
You can buy his book, The Startup Owner's Manual here:
You can buy his book, The Startup Owner's Manual here:
Steve Blank
Blank is known primarily as a theoretician, although he has founded and advised many companies. His ideas have been very influential in the culture.
What's A Startup?
Blank has been thinking about startups for a while, so his blog post are focused, but peppered with reference to other areas where he expands on the topic.
He gets right to the point:
In this post we’re going to offer a new definition of why startups exist: a startup is an organization formed to search for a repeatable and scalable business model. (Blank)And then he unpacks the idea of a business model.
A business model describes how your company makes money. (Blank)So a startup is an organization formed to search for a repeatable and scalable way to make money. That sounds like any business. What sets Blank's theory apart is probably the detailed process he lays out to form such a business.
Q: Peter Thiel seems to disagree with Blank's model. In particular he advises startups to have big bold plans, that can be modified indefinitely, which deliver an enormous innovation that earns a monopoly. Blank doesn't think this contradicts his own view. Do readers think there is a fundamental distinction here?
The Business Model Canvas
Blank is a fan of the Alexander Osterwalder's Business Model Canvas , which is a template to organize the components of a business.
Startup as hypothesis testing
Blank has specific advice on the role of a founding team.
Your job as a founder is to quickly validate whether the model is correct by seeing if customers behave as your model predicts. Most of the time the darn customers don’t behave as you predicted. (Blank)The benefit of this advice is it focuses energies on hypothesis testing early on.
Contrast: Although Thiel has claimed that this advice contradicts to come up with a long term plan, the tenure of the plan doesn't seem to be a central component of Blank's thesis. There is something about the MVP that feels small and timid, compared to Thiel's idea of going from 0 to 1 which feels ambitious and large in scale. The question is, if Blank had used a different word -- Initial Hypthesis Product, for instance -- would there still be a fundamental disagreement?
Q: Blank realizes of course that experimentation can be very expensive. You can't usually launch an entire business to see if customers like it, so his idea is to put out a really simple minimal viable product and use that to test it.
The big criticism -- and I am not the first to make it -- is this contrast directly with advice from other people.
Famously, Steve Jobs said in an interview:
"It's not about pop culture, and it's not about fooling people, and it's not about convincing people that they want something they don't. We figure out what we want. And I think we're pretty good at having the right discipline to think through whether a lot of other people are going to want it, too. That's what we get paid to do.This is not the first time Jobs had said this.
"So you can't go out and ask people, you know, what the next big [thing.] There's a great quote by Henry Ford, right? He said, 'If I'd have asked my customers what they wanted, they would have told me "A faster horse." ' "(Steve Jobs)
Blank is well aware of this criticism, but I don't know that he fully takes on the problem.
You can buy his book, The Startup Owner's Manual here:
Subscribe to:
Posts
(
Atom
)